Fraud prevention
Lendgo Loans Safety: How to Spot a Loan Scam
Loan scams prey on urgency. Knowing the warning signs, and how to check a lender in a few minutes, protects your money and your identity.
Loan scams work because they show up when people feel pressure: a bill is due, a car needs repair, or a family member needs help fast. Anyone researching lendgo loans or any other personal loan option can run into fake offers that look polished, use familiar logos and promise easy money. The goal of a scam is simple. It wants your cash, your bank login or enough personal information to open accounts in your name. This guide covers the most common red flags, how to verify a real lender in a few minutes, and exactly what to do if you think you have been targeted. Share it with anyone in your family who might get a convincing call or email.
Why loan scams work
Loan scams succeed by combining urgency, a promise that sounds easy, and a request that seems small at the moment, such as a fee or a login. People under financial stress are more likely to act quickly, and scammers count on that.
Most scams follow a script. First, an offer arrives by text, email, phone or social media, often unsolicited. Next, it promises something real lenders do not: that approval is certain, that your credit won't be looked at, or that a large amount can be wired within the hour. Finally, it asks for something that benefits the scammer: an upfront payment, a gift card code, your online banking password or a photo of your ID.
A fake personal loan offer is often timed to arrive right after you search for one. Older adults are frequent targets, but so are younger borrowers with thin credit files who may feel they have few options. Talking openly about money in your family, as awkward as it can be, is one of the best protections there is.
Red flag: fees before you get the money
A demand for payment before a loan is funded is one of the clearest signs of fraud. Legitimate personal loan lenders typically deduct any origination fee from the loan proceeds or add it to the balance, rather than asking you to send money first.
Scammers dress up upfront fees with official-sounding names: "insurance," "processing," "first payment," "collateral deposit" or "verification fee." The amount is often a few hundred dollars, small enough to feel worth it when you are expecting $2,000 or $5,000. Once you pay, the loan never arrives, or a second fee appears.
Real personal loan costs are disclosed in writing before you sign. Origination fees commonly range from 0% to about 10% of the amount, and they are usually subtracted from what you receive. Our glossary explains origination fees, APR and other terms you should see in a genuine loan agreement.
Red flag: gift cards, wires and crypto
Any request to pay with gift cards, wire transfers, cryptocurrency or a payment app sent to an individual is a major warning sign. Legitimate lenders collect payments through traceable methods such as automatic bank debits or their own payment portal.
Scammers prefer payment methods that are fast and hard to reverse. A gift card code read over the phone is gone the moment you share it. A wire transfer can be withdrawn within minutes. Crypto transfers are rarely recoverable. If anyone tells you to buy gift cards, visit a crypto ATM or send money to a person rather than a business account, stop the conversation.
A related trick is the overpayment scam. The fraudster deposits a fake check or a small transfer, claims it was too much, and asks you to send the difference back. The original deposit later bounces, and you lose the money you sent.
Red flag: pressure and secrecy
High-pressure tactics, such as offers that expire in minutes, threats that you will lose your approval, or instructions not to talk to anyone, are hallmarks of fraud. Real lenders give you time to read the terms and do not object if you ask questions.
Watch for phrases like "this offer ends today," "you must decide now," or "do not tell your bank, they will block this." Real loan offers come with written disclosures you can review. Lenders know borrowers compare options, and many lenders even encourage it.
Be especially wary of anyone who says your credit won't be looked at, or that approval is certain regardless of your history. Legitimate lenders review applications before making decisions, and most check credit in some form. A promise that skips that step is often the hook for an upfront fee.
Red flag: unlicensed lenders and spoofed sites
Lenders generally must be licensed or registered to lend in your state, and scammers often skip that step or copy the name and look of a real company. Spoofed websites may use a nearly identical web address with one letter changed.
Signs of a spoofed or fake lender site:
- A web address that is slightly off from the company's real domain, or uses odd endings.
- No physical address, or one that turns out to be a mailbox or vacant lot.
- Contact only through a mobile number, a chat app or a free email account.
- Spelling errors, blurry logos or pages that say very little about loan terms.
- Reviews or ratings that cannot be verified anywhere else.
Type a lender's address directly into your browser rather than clicking links in texts or emails. Bookmark the real site once you have confirmed it.
Red flag: requests for passwords and codes
No legitimate lender needs your online banking password, your email password or the one-time verification codes your bank texts you. Anyone asking for those is trying to take over your accounts, not lend you money.
Some lenders use secure third-party services to verify bank account information, and those services show you a clear authorization screen. That is different from someone on the phone asking you to read back a code or share a password. Your bank's verification codes exist to stop exactly this kind of access.
Also be careful with your Social Security number, full date of birth and photos of your ID. Real lenders do ask for some of this information, but only through a secure application on their verified site, not by text or social media message.
What a legitimate personal loan offer looks like
A legitimate personal loan offer comes in writing with the lender's legal name, license information, APR, finance charge, total of payments and payment schedule, and it gives you time to review before you sign. Nothing is due until the loan is funded.
Knowing what normal looks like makes the fakes easier to spot. A typical personal loan for $500 to $5,000 carries an APR of about 6% to 35.99% across lenders, with terms of roughly 3 to 36 months. As a representative example, $2,000 borrowed for 12 months at 24.99% APR works out to about $190.08 a month, $2,280.94 total and $280.94 in interest. An offer far outside those ranges, in either direction, deserves a closer look.
Real personal loan lenders also follow a recognizable process:
- They review your information first. Most check credit in some form and verify income before making a final decision.
- They disclose costs before you commit. You see the APR and total of payments on a written disclosure, not just a monthly figure over the phone.
- They fund to your own bank account. Money arrives by direct deposit, often the next business day after approval, sometimes the same day, depending on the lender and your bank.
- They collect payments through traceable channels. Expect automatic debits or the lender's own payment portal.
- They let you walk away. If you decline an offer before signing, you owe nothing.
Whether you found an offer by comparing lendgo loans or through a mailer, the checklist is the same. If a personal loan offer is missing any of these pieces, slow down and verify the lender before you go further. A genuine personal loan can wait a day while you check; a scam usually cannot.
How to verify a lender in minutes
Verify a lender by checking its license with your state's financial regulator, searching the company in the NMLS Consumer Access database, confirming its contact details independently, and reading its written disclosures before you share sensitive information.
- Check your state regulator. Every state has an agency that licenses consumer lenders, often a department of financial institutions or banking. Search its license lookup for the lender's exact legal name.
- Search NMLS Consumer Access. The Nationwide Multistate Licensing System lets you look up many state-licensed lenders by name or NMLS ID number. Compare the address and name to what the lender shows you.
- Confirm contact details yourself. Find the lender's phone number through its verified website or your state regulator, then call that number rather than one in a message.
- Read the disclosures. A real offer shows the APR, finance charge, amount financed, total of payments and payment schedule before you sign.
- Search the company name with words like "complaint" or "scam." A pattern of reports is worth taking seriously.
Our how it works page explains how our service operates: one short request form shared with lenders in our network, who review it and decide on any offer. There is no fee to use our service and no obligation to accept an offer, and we never ask for upfront payments. If you want to see which lenders appear in our network, the compare lenders page lists them.
What to do if you've been targeted
If you think a scammer has contacted you, stop all communication, contact your bank right away, change any passwords you shared, and report the scam to the Federal Trade Commission through ReportFraud and to your state attorney general.
Act quickly, in this order:
- Stop responding. Do not send more money or information, even if the scammer threatens you.
- Call your bank or card issuer. Ask them to stop or reverse any payments if possible and to watch for unusual activity. For gift cards, contact the card company with the card numbers and receipts.
- Change passwords. Update your banking and email passwords and turn on two-step verification.
- Report it. File a report with the Federal Trade Commission through its ReportFraud service, and contact your state attorney general's consumer protection office. You can also file a complaint with the Consumer Financial Protection Bureau, the federal consumer-finance regulator.
- Protect your credit. If you shared your Social Security number, consider a credit freeze with each of the three national credit bureaus. A freeze stops new accounts from being opened in your name and is free.
- Watch your accounts. Check bank statements and credit reports for anything you do not recognize over the coming months.
Keep notes: dates, phone numbers, names used, amounts and screenshots. Those details help investigators and your bank.
Beware of recovery scams
After a scam, some victims get calls from people promising to recover lost money for a fee. These are often the same scammers or their partners. Real government agencies do not charge fees to recover money.
Safe habits for lendgo loans shoppers
Safe borrowing habits include starting from a site you typed yourself, comparing at least two written offers, never paying to receive a loan, and pausing a day before signing. A few minutes of checking can prevent months of cleanup.
People who search lendgo loans or lendgo personal loans are usually comparing several options quickly. Speed is fine, as long as the checks above happen first. Keep this short list handy:
- Look for the APR and total of payments in writing on every personal loan offer.
- Confirm licensing with your state regulator or NMLS.
- Refuse any request for fees before funding, gift cards or passwords.
- Use only verified websites, typed in directly.
- Talk it over with someone you trust before signing.
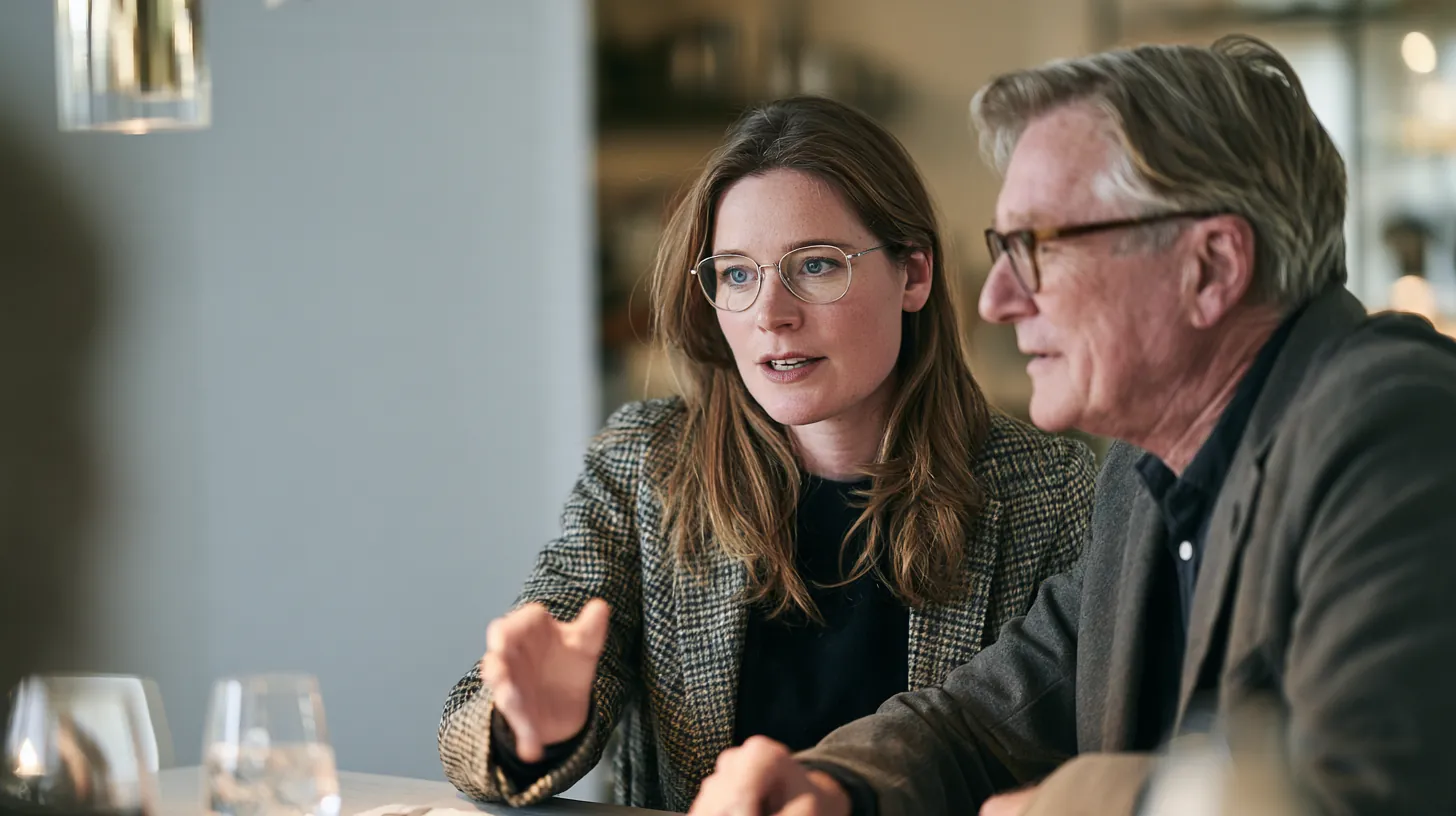
That last habit matters more than it sounds. A quick conversation with a family member, like a daughter walking her father through an offer at the dining table, often catches the red flag the borrower missed under stress. Checking lendgo rates and reading real disclosures takes a few minutes; recovering from a scam can take far longer.
Questions
Frequently asked questions
Is it normal for a lender to charge a fee before the loan is funded?
Legitimate personal loan lenders typically deduct any origination fee from the loan proceeds or add it to the balance, rather than asking you to pay upfront. A request to send money before you receive the loan, especially by gift card or wire, is a strong sign of fraud.
How can I tell if a loan website is fake?
Check the web address carefully for small misspellings, look for a verifiable physical address, and confirm the lender's license with your state regulator or NMLS Consumer Access. Type the address yourself instead of clicking links in messages.
Where do I report a loan scam?
Report it to the Federal Trade Commission through ReportFraud and to your state attorney general's consumer protection office. You can also submit a complaint to the Consumer Financial Protection Bureau. Contact your bank right away if you sent money or shared account details.
About the author
Written by Teresa Calloway
Keep reading
Related posts
Lendgo Loans: Secured or Unsecured, Which Fits?
How secured and unsecured personal loans differ on collateral, rates, risk and approval, with a side-by-side table and clear guidance on who each fits.
Lendgo Loans: What Credit Score Do You Need?
FICO score bands explained, what lenders look at besides your score, how soft-pull prequalification works, and practical ways to improve your approval odds.
Free to use · No obligation
Ready to compare personal loan offers?
One short request, no fee to use our service and no obligation to accept an offer.